The deck that raised — and the slides I'd cut now.
In July 2021 this is the deck that brought ZX Ventures, AB InBev and RMB together as co-investors in The Duchess. Five years on, I've ripped it apart slide by slide — what worked, what's off in hindsight, and what I'd cut if I were rebuilding it today.
How I'm reading this
- Quiet-luxury covers worked then because we ran on warm intros only. In 2026 a deck has to survive cold-forwarding. Cover should carry round + ask + contact even for warm channels.
- Timeline-as-traction is the move I underused. Slide 6 (the 2016–2021 trajectory) is the slide that closed AB InBev. I'd reuse this pattern in every deck I've built since.
- Internal quotes aren't social proof. Talita as "Global Marketing Manager" speaking to The Duchess's positioning was a familiar founder mistake — investors discount internal voice.
- Brand vs. product slides need to earn rent. Slide 3 ("Refresh Your Mind") and slide 11 (cans) both ride on photography. Both could carry one number and become 10× more useful.
- Recap slides keep being the weakest slide of every deck I've built. "A passionate team" / "Beautiful brand" — these are descriptors, not arguments.
Want the original PDF?
Drop your email and I'll send you the unannotated deck.
Same 18 slides as below, in the original Keynote layout — useful as a structural reference for your own raise.
One email, no list, no follow-up unless you ask. Privacy.
Slide 1 of 18
Cover — The Duchess Alcohol-Free Drinks · Investment Proposal
Worked. Quiet luxury. Reads like a Champagne house's pitch. That alone telegraphed positioning to AB InBev — premium, design-led, sober adult drinks.
Off (in hindsight). No raise size, no ask, no investor on the cover. Worked because every recipient came via warm intro. In 2026 even warm intros benefit from a cover-line — saves the recipient one slide of figuring out the basics.
Today's fix. Sub-line on the cover: "Series Seed Extension · Raising $1.5M · Cape Town, July 2021 · johannes@theduchess.co.za". Clean.
Slide 2 of 18
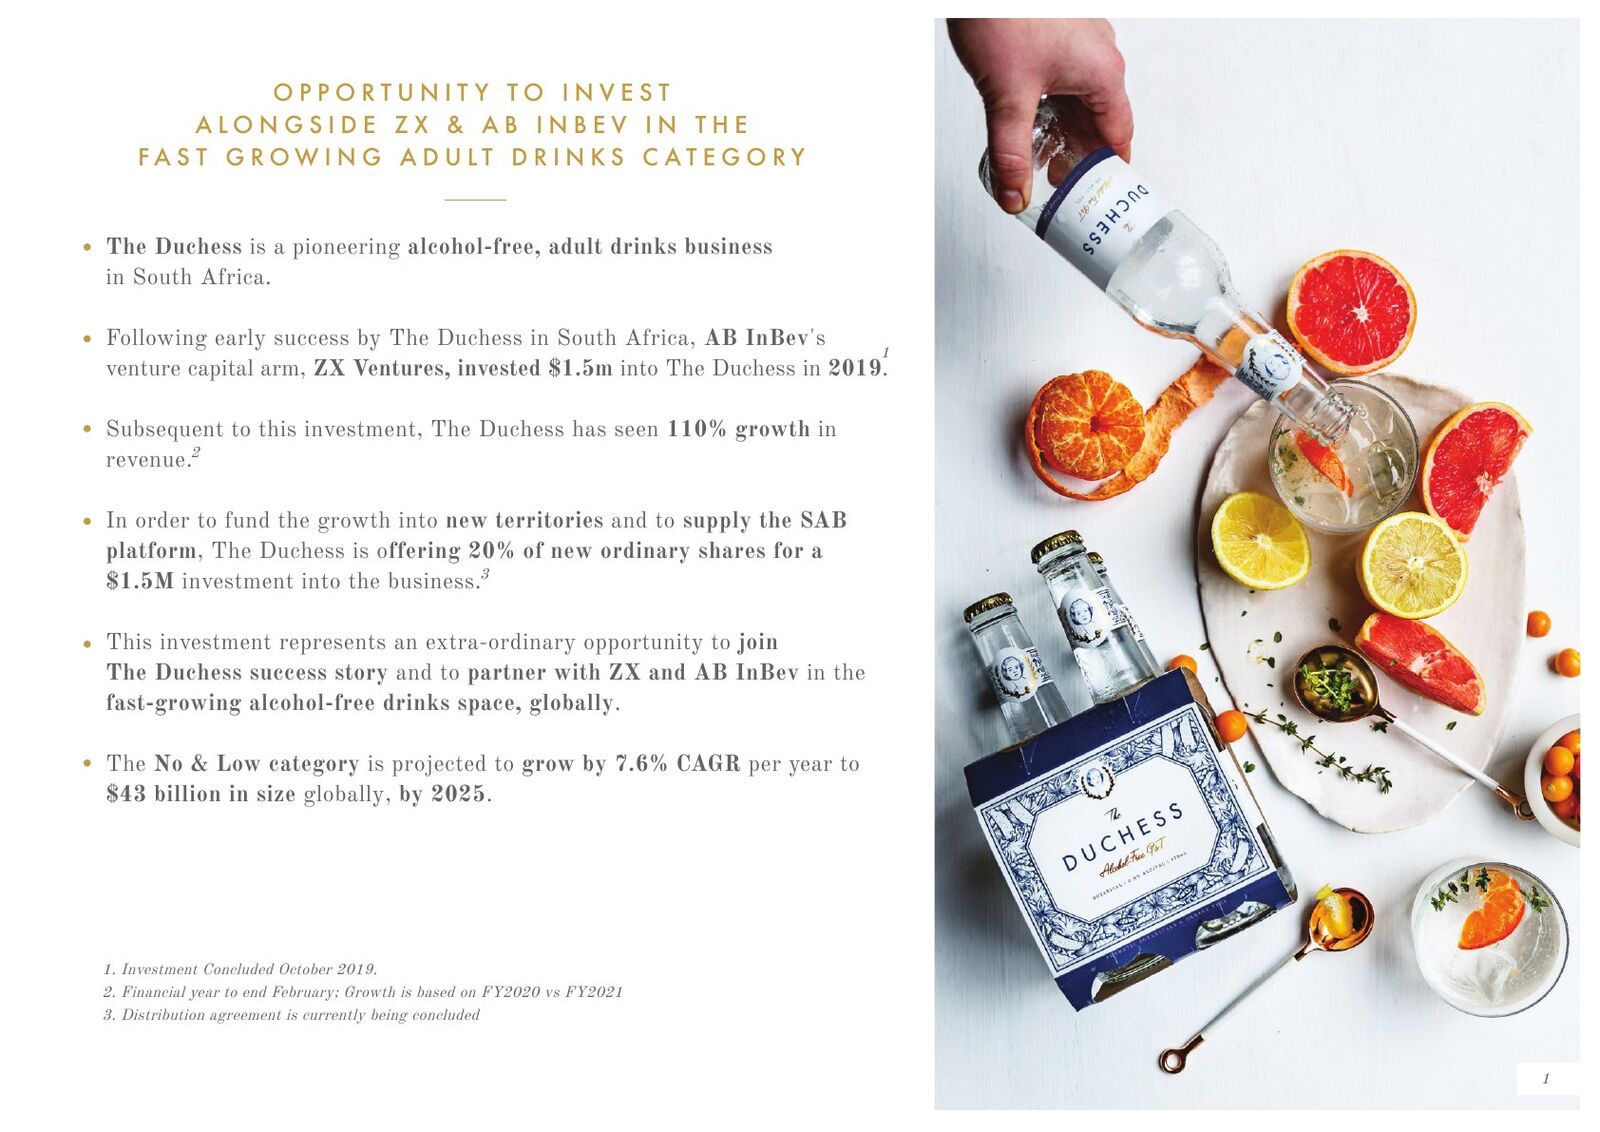
Opportunity to invest alongside ZX & AB InBev
Worked. Strongest slide in the deck. "ZX Ventures invested $1.5M in 2019 → 110% revenue growth → SAB platform unlocking" is the entire story in three lines.
Off (in hindsight). 110% growth needs a base. 110% of what? $200K → $420K is a different story than $5M → $10.5M.
Today's fix. One sentence. "From $X in FY2020 to $Y in FY2021." No reader should have to do the math.
Slide 3 of 18
Refresh Your Mind
Worked. Aspirational mood imagery on a single line. Brand on a page.
Off (in hindsight). Beautiful but empty. A 2026 read: this is a brand-book slide, not a deck slide. A deck is a sales tool, not a lookbook.
Today's fix. Earn the white space with one stat. "1.6M bottles of Refresh Your Mind sold in 2020." Make the mood pay rent.
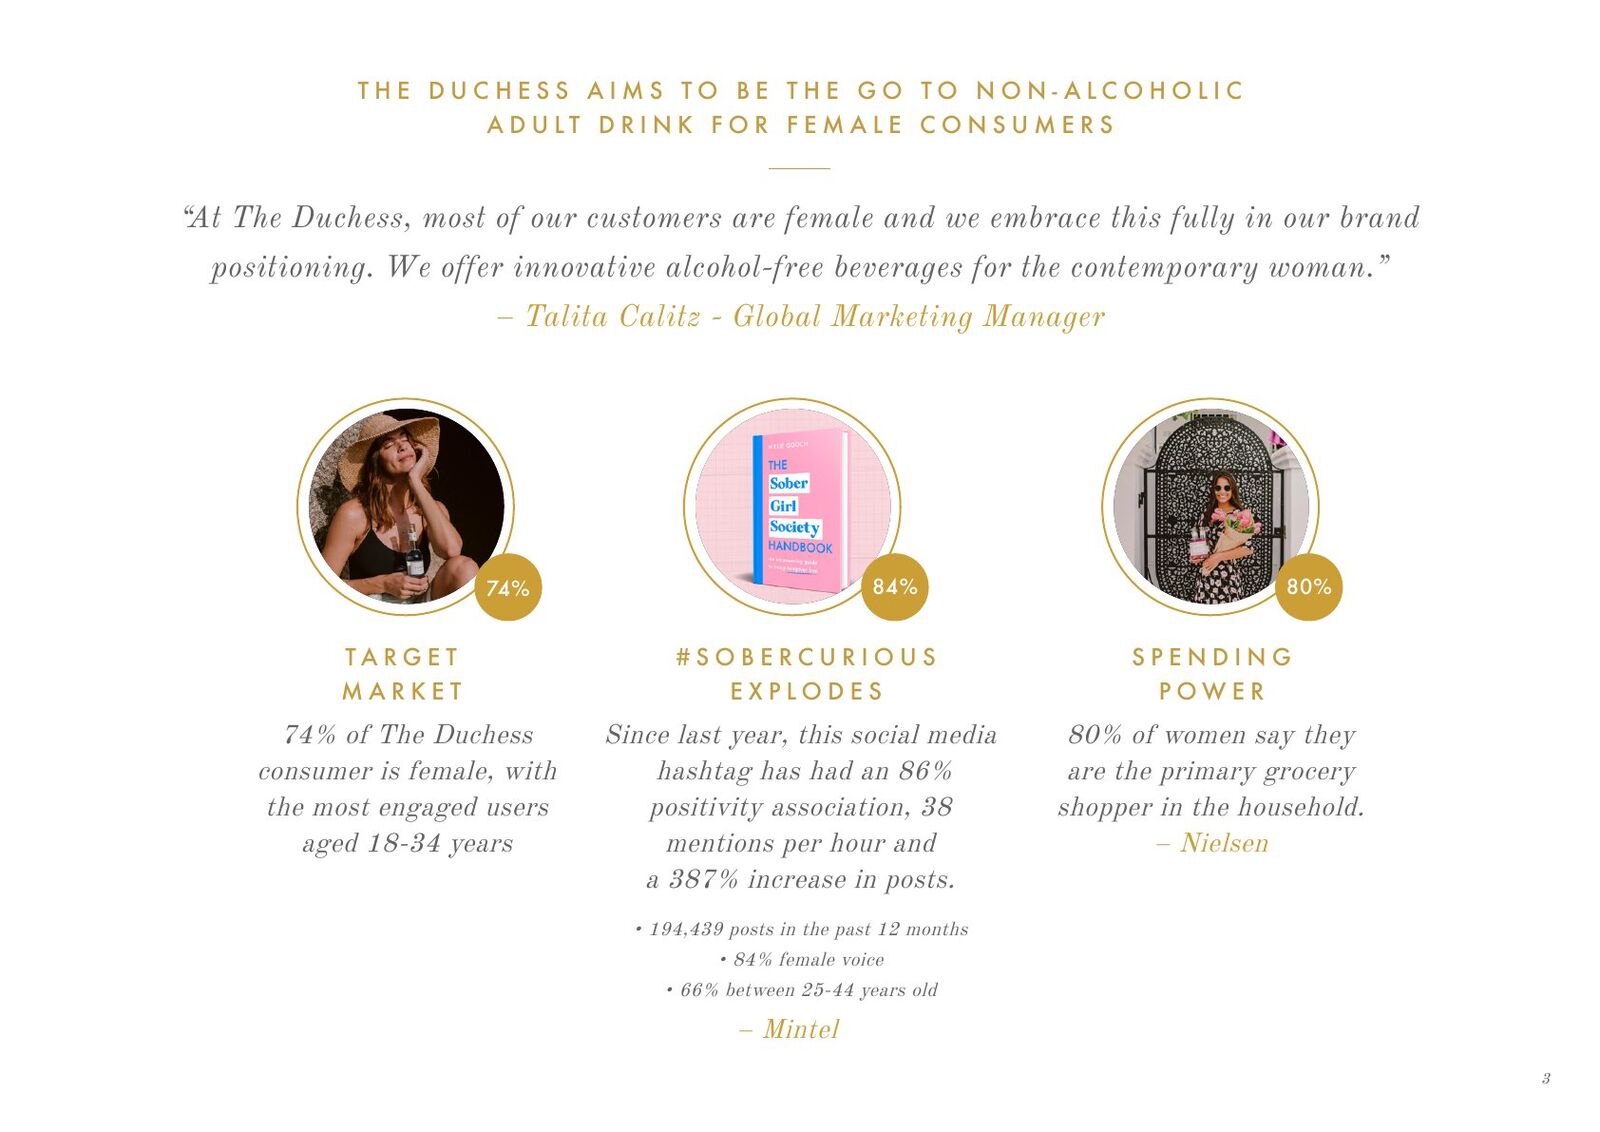
Slide 4 of 18
The Duchess aims to be the go-to non-alcoholic adult drink for female consumers
Worked. Clear ICP (74% female, 18–34). Three trust signals — #sobercurious explosion, female grocery-purchase power, Mintel data behind it.
Off (in hindsight). Talita Calitz quoted as "Global Marketing Manager." Internal voice doesn't count as social proof. Worse: an internal quote about who our customer is implies we declared the customer; we didn't earn it externally.
Today's fix. Replace the internal quote with a Pick n Pay buyer quote, or a category manager from Albert Heijn or Dan Murphy's. Internal proves you believe; external proves they believe. Investors weight the latter 10×.
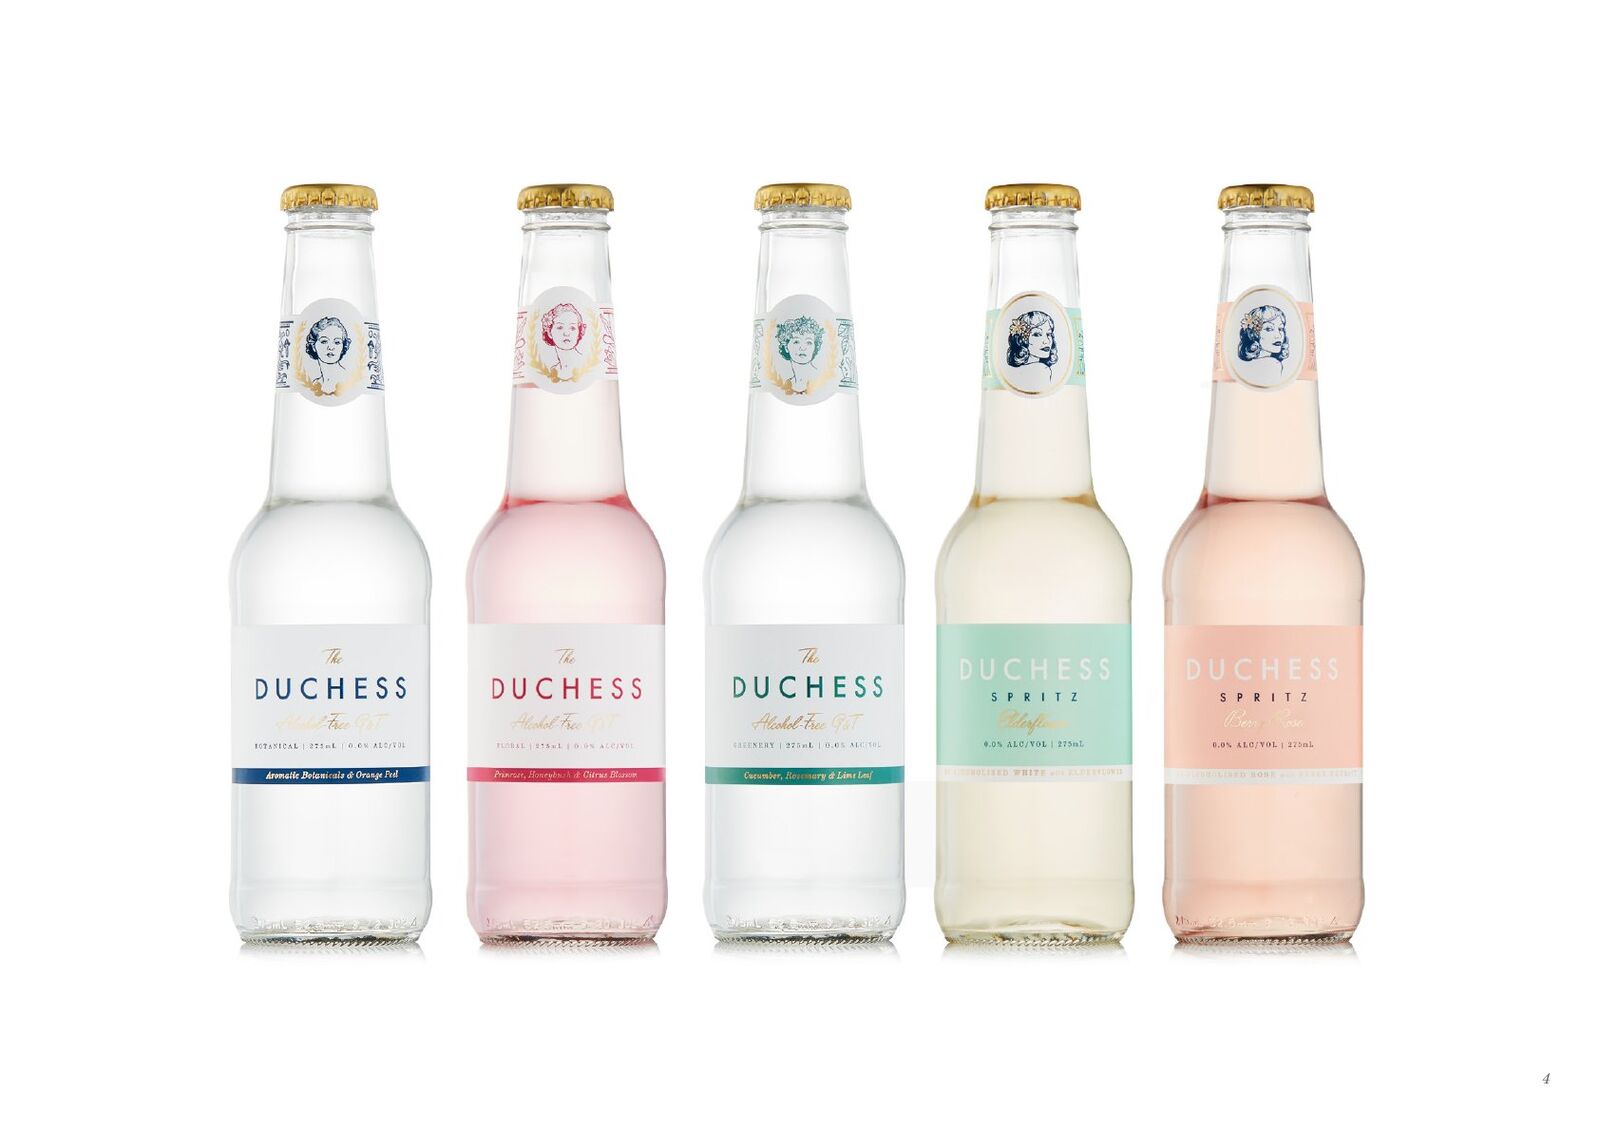
Slide 5 of 18
Product range — five SKUs
Worked. Beautiful product photography. Five SKUs telegraphed "we're not a one-trick pony."
Off (in hindsight). No spec, no occasion, no price. And — bigger — two of the five are Spritzers at 6% ABV, which contradicts the "Alcohol-Free Drinks" line on the cover. The 0% promise breaks at slide 5. A buyer who reads carefully will pause here.
Today's fix. Either reframe the cover as "alcohol-free + low-ABV adult drinks" (which is what AB InBev cared about anyway), or pull the spritzers from this deck and pitch them as a separate range. Inconsistency between cover-promise and product-page costs trust mid-meeting.
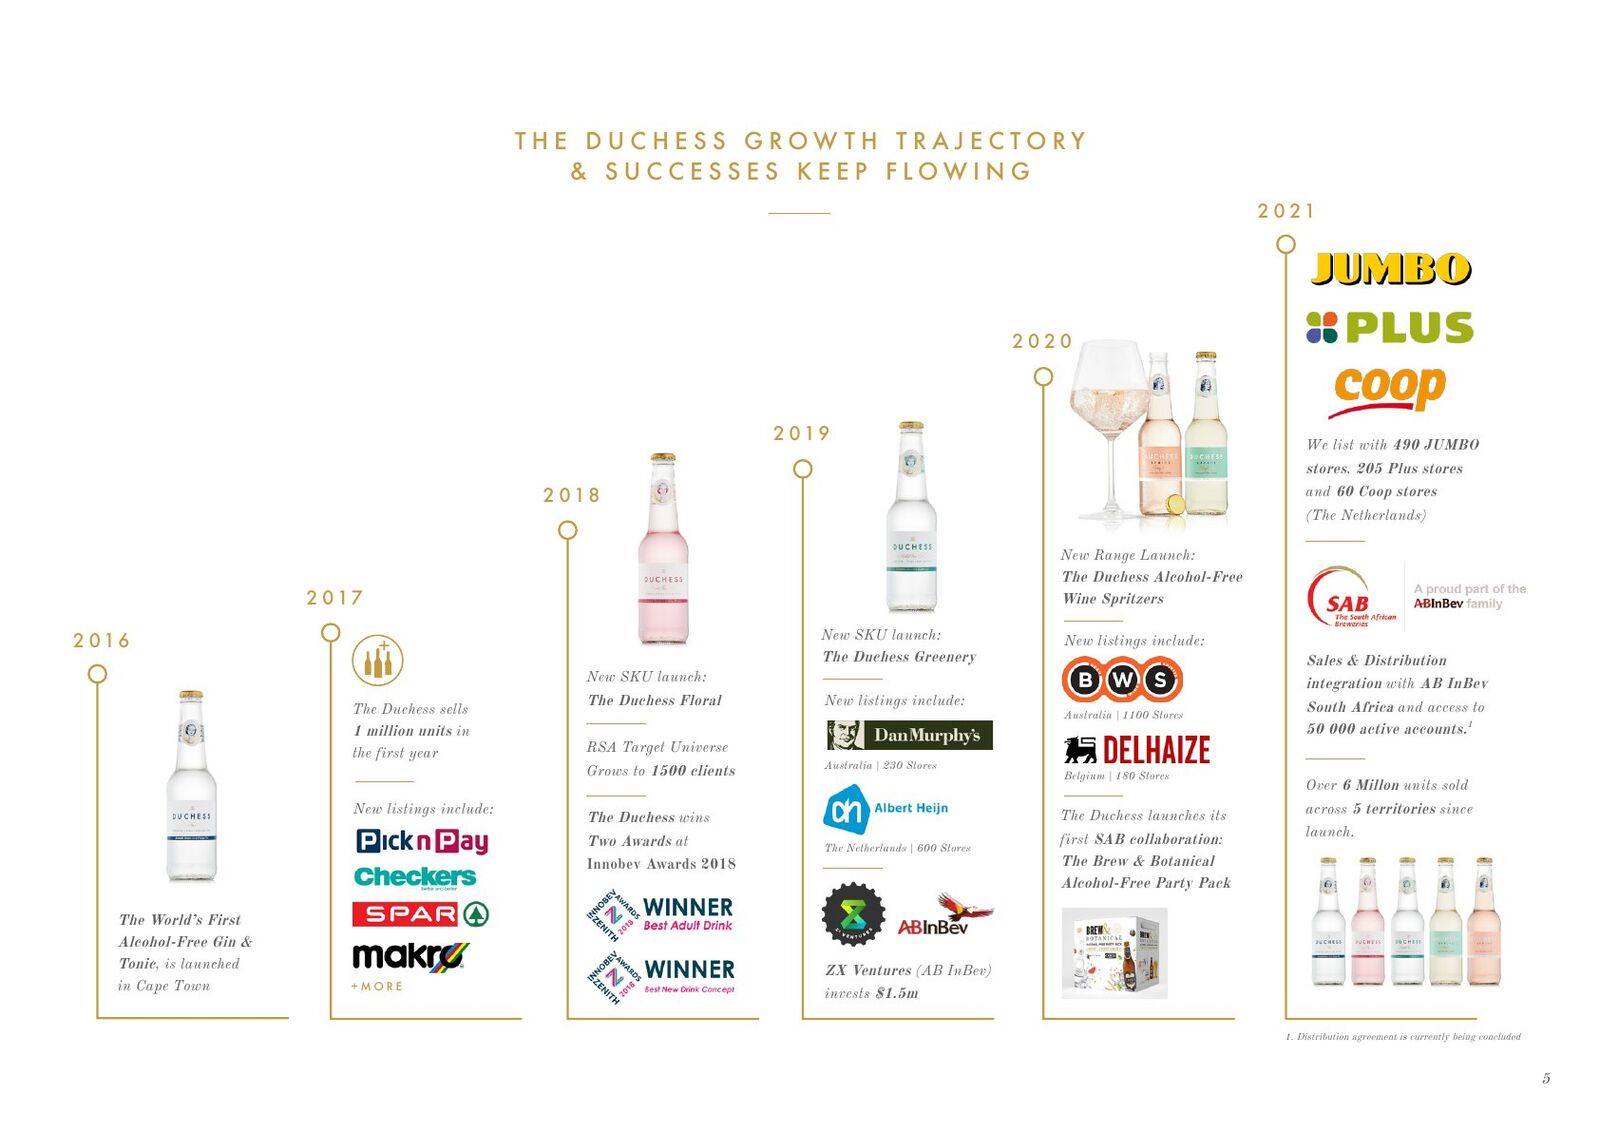
Slide 6 of 18
The Duchess growth trajectory & successes (2016–2021)
Worked. Best timeline I've ever drawn. Five years of evidence in ten seconds — "World's First 0% G&T launched in CT" through to "490 JUMBO + 205 Plus + 60 Coop stores + ZX Ventures investment." Awards, retailer logos, year-by-year SKU launches. This is the slide that closed the partnership.
Off (in hindsight). Nothing. This is a working slide.
Today's fix. Lesson for self: timelines work because they make traction physical. The reader walks five years of evidence in ten seconds. Reuse this pattern in every deck I build going forward.
Slide 7 of 18
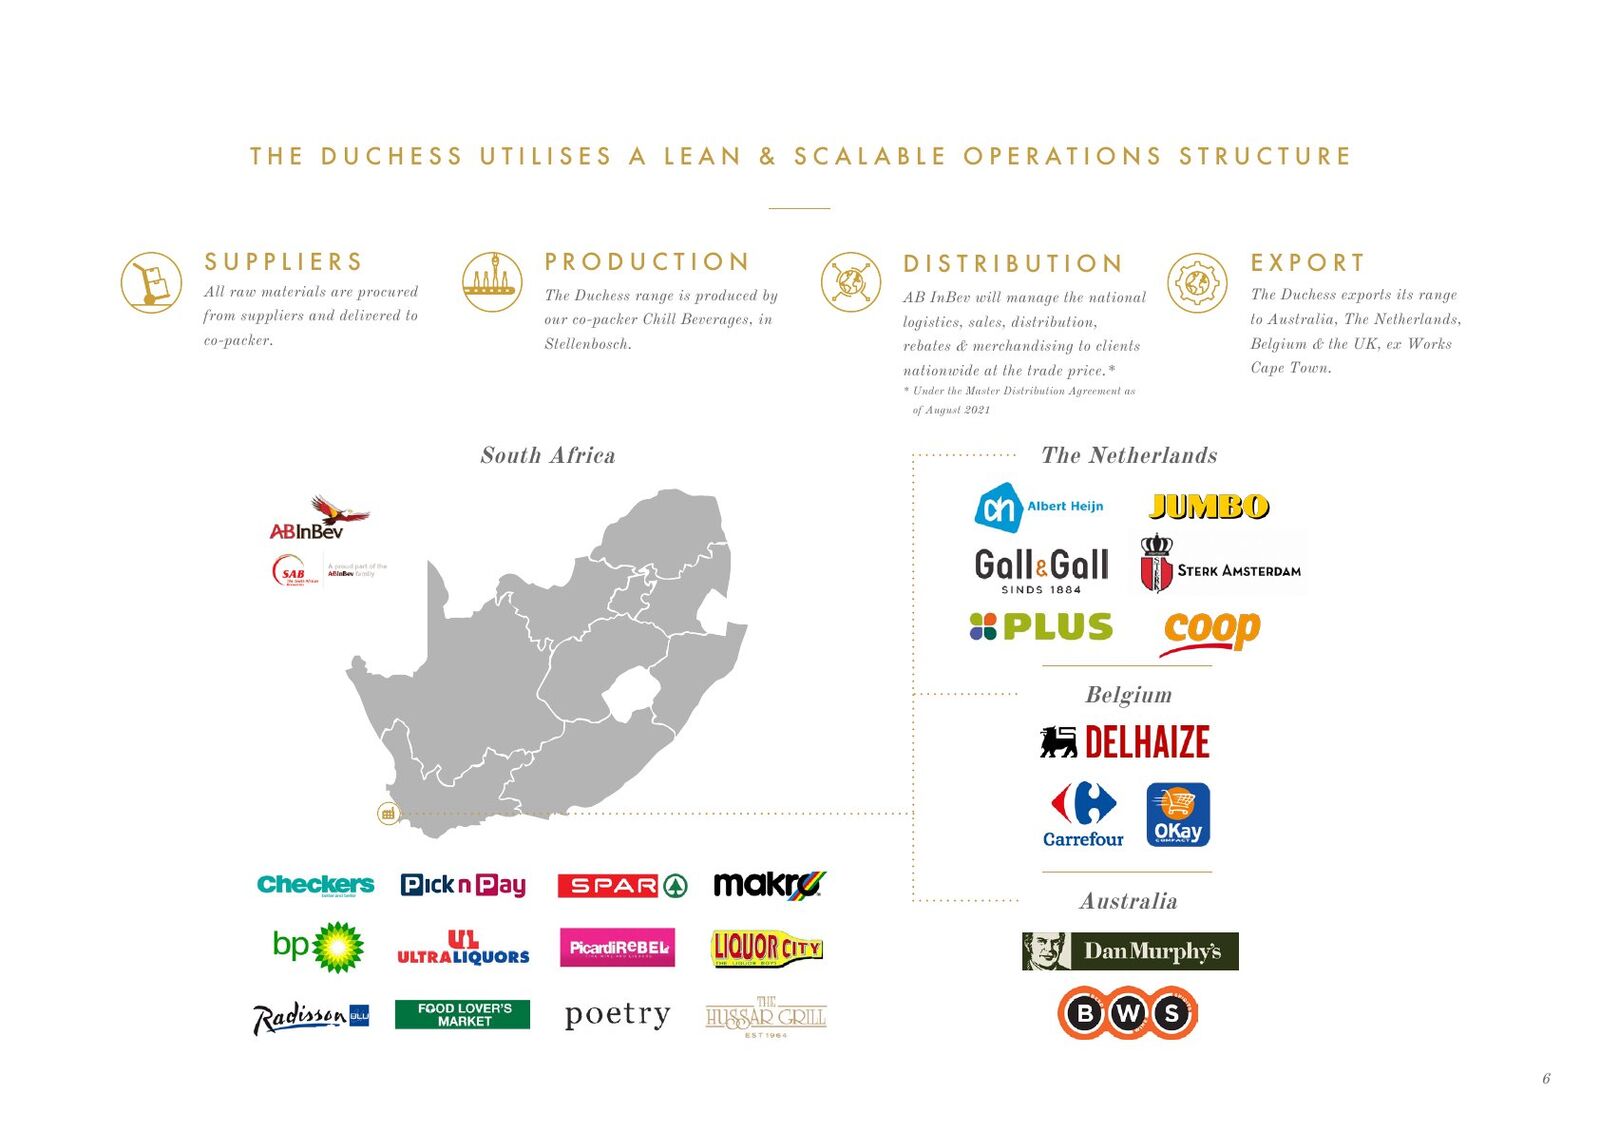
The Duchess utilises a lean & scalable operations structure
Worked. Lean ops shown clearly. AB InBev managing distribution = the value-prop visualised.
Off (in hindsight). Shows the plumbing but not the economics. AB InBev managing distribution at trade price compresses margin — should have shown deal terms.
Today's fix. One-line economics summary: "Co-pack at R{} per bottle, AB InBev distributes at trade price + {}% rebate, net margin to Duchess R{} per bottle." Without that, investors model conservatively or skip.
Slide 8 of 18
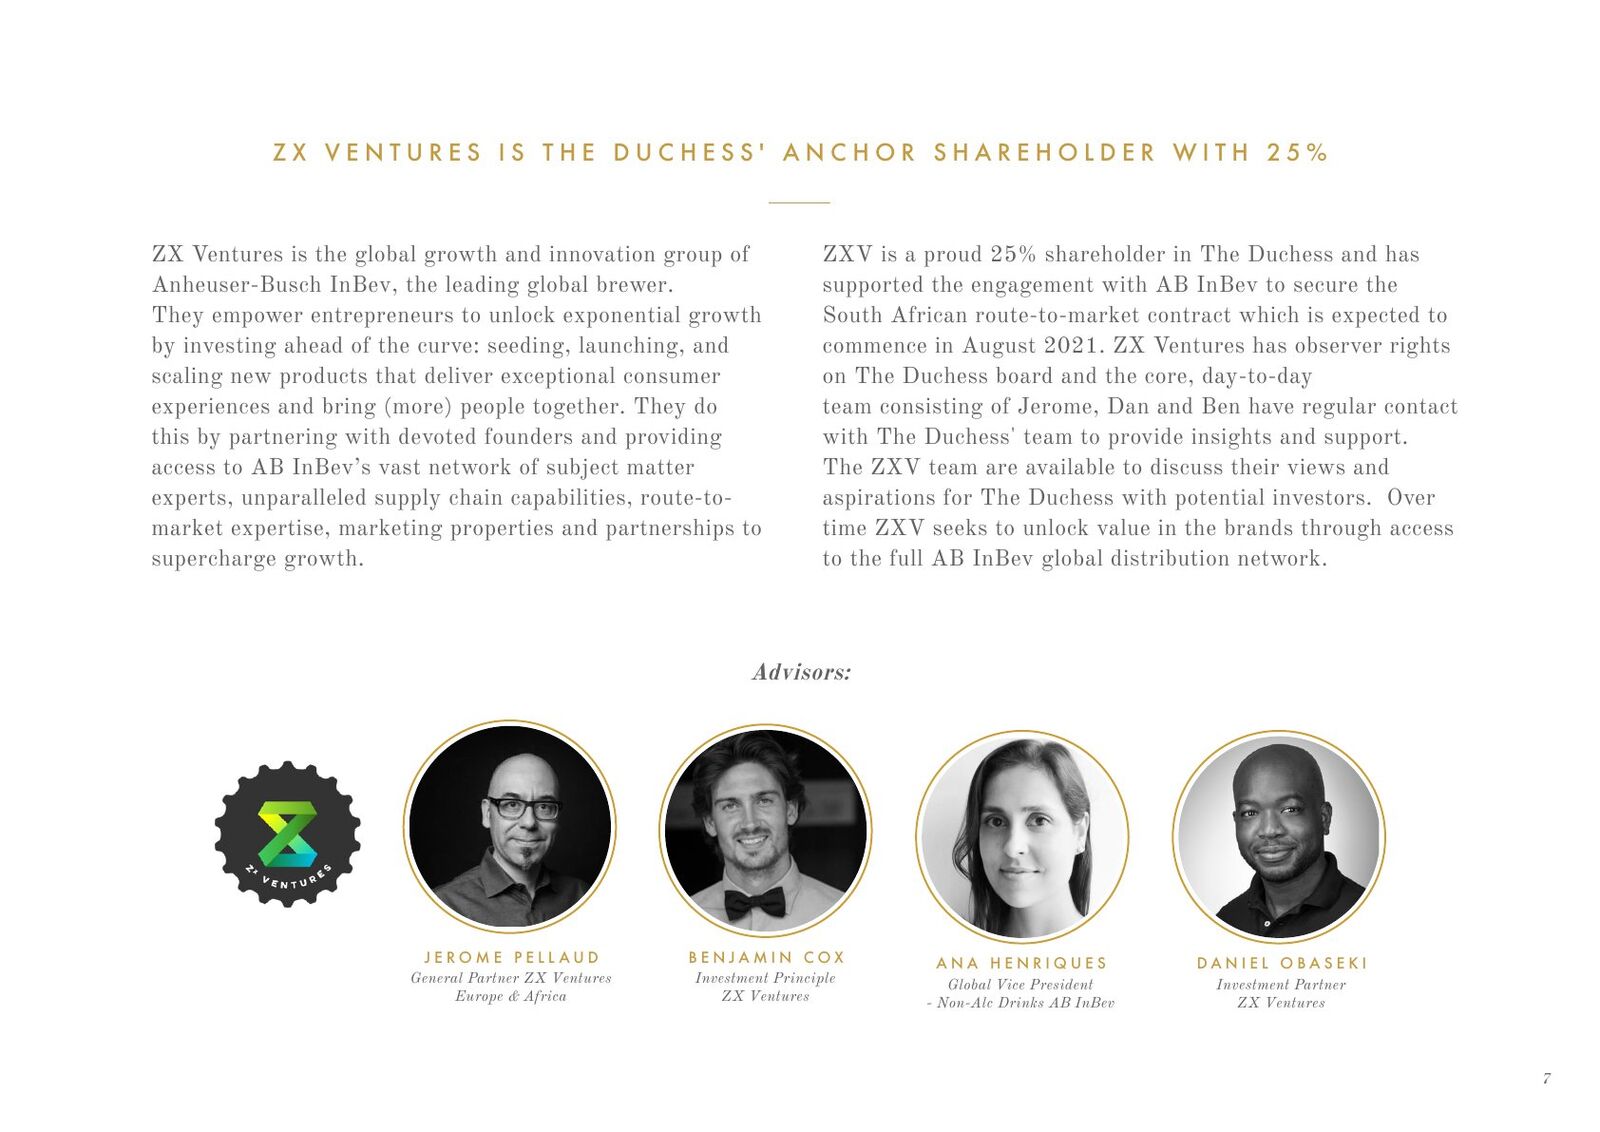
ZX Ventures is The Duchess' anchor shareholder with 25%
Worked. Anchor investor + four named advisors with credible roles. ZX/AB InBev brand is the credibility multiplier.
Off (in hindsight). Two paragraphs of corporate prose. Reader needs one thing — "ZX owns 25%, AB InBev distributes us nationally, here are the four humans who help."
Today's fix. One-sentence summary at the top, then the photos. Save reader bandwidth.
Slide 9 of 18
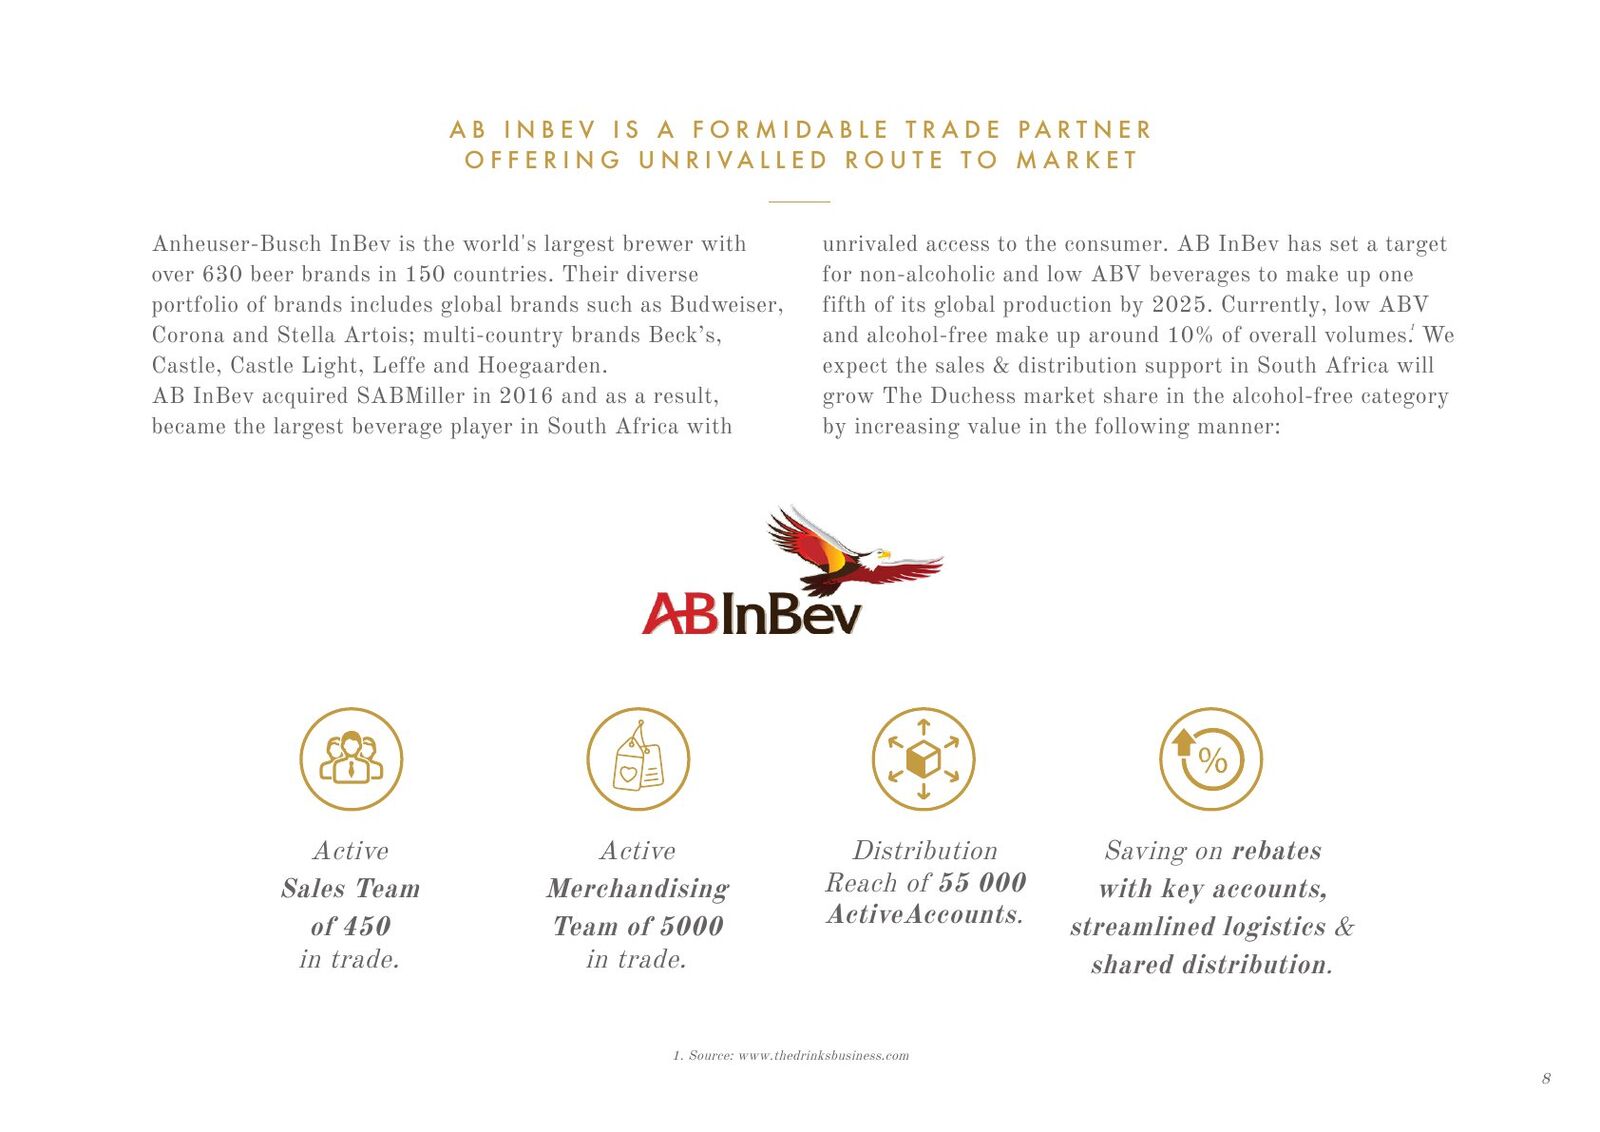
AB InBev is a formidable trade partner offering unrivalled route to market
Worked. The moat slide. 450 sales reps, 5,000 merchandisers, 55,000 active accounts, AB InBev's 20% non-alc target. That's the slide that tells the investor "you're buying access to the largest beverage distribution machine in SA on day one."
Off (in hindsight). Slide 9 is too late for this. Second-most-important slide in the deck (after slide 6), hidden behind a generic mood slide and a product slide.
Today's fix. Reorder. Cover → ZX/AB InBev partnership punchline (current slide 2) → AB InBev moat (current slide 9) → Timeline (current slide 6) → Market → Product → Team → Financials → Ask. Lead with what they're buying access to.
Slide 10 of 18
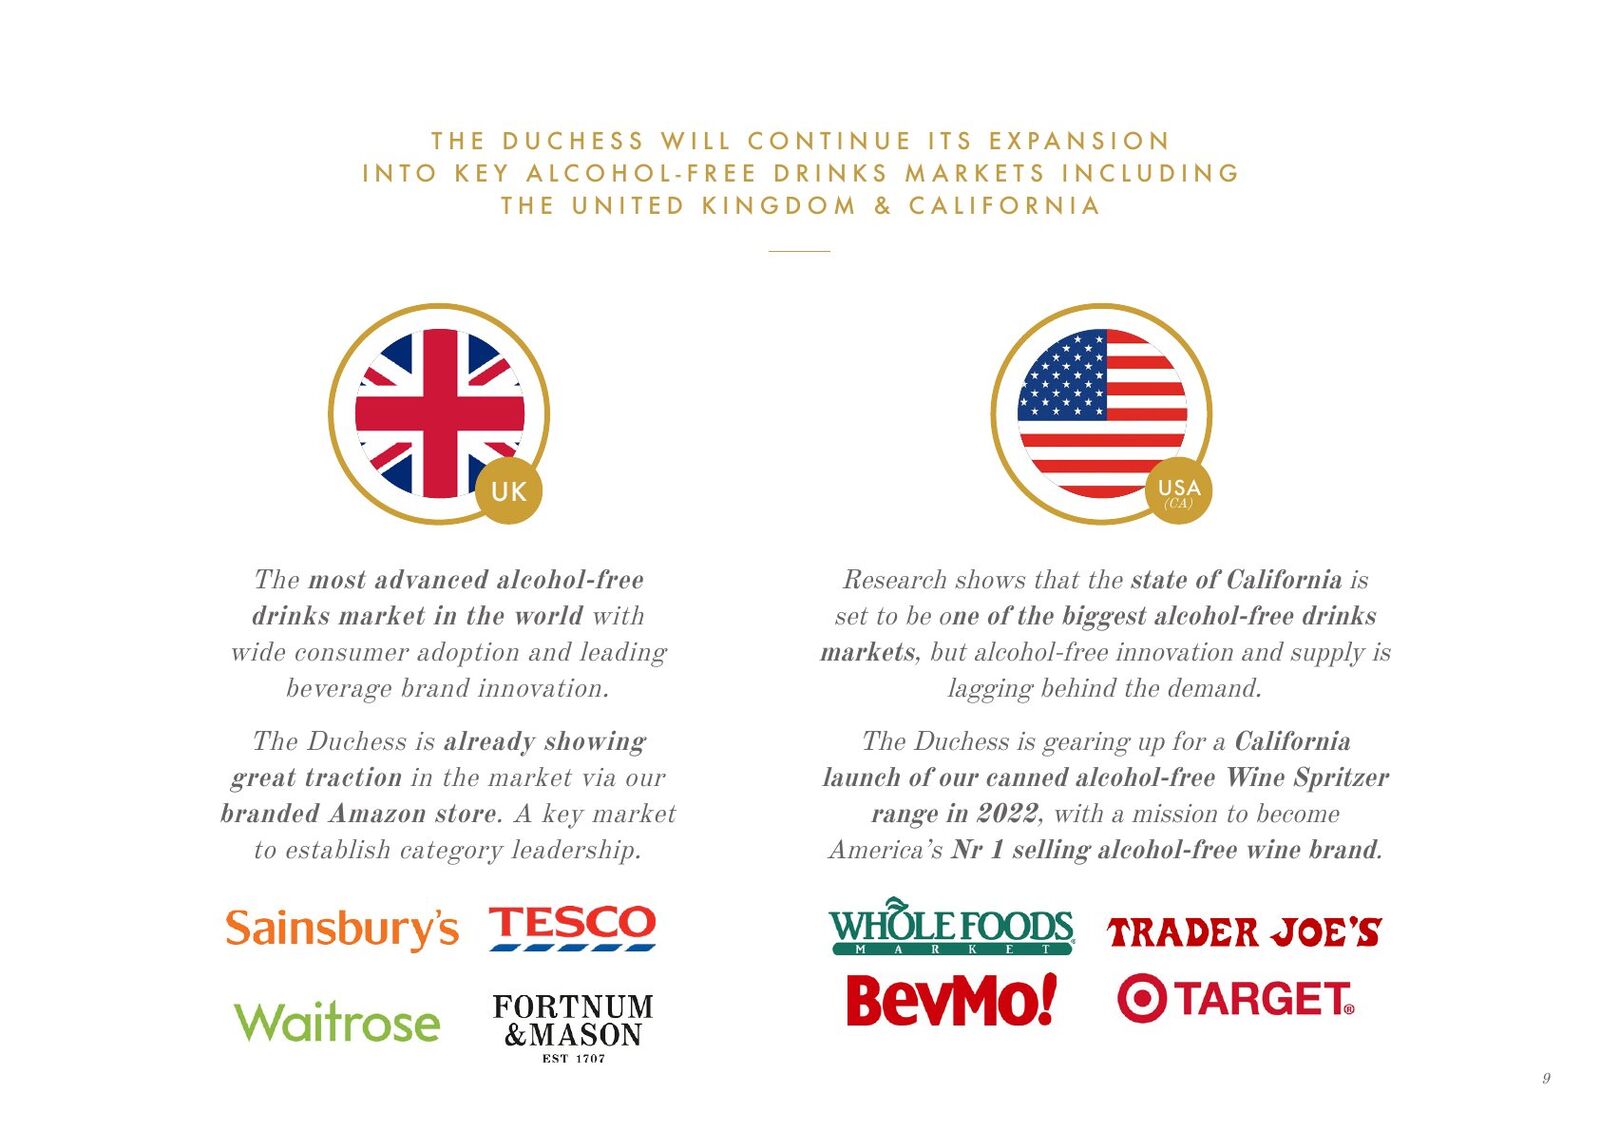
The Duchess will continue its expansion into key alcohol-free markets
Worked. Concrete next markets, named retailers — Sainsbury's, Tesco, Whole Foods, Trader Joe's.
Off (in hindsight). Reader can't tell which retailers are signed vs. pipeline. A target list reading like an LOI list is a common founder slip — and CPG buyers (the target audience for this deck) catch it instantly.
Today's fix. Two columns. Live (Dan Murphy's, Albert Heijn, BWS) vs. Pipeline (Tesco, Whole Foods, Sainsbury's). Don't conflate.
Slide 11 of 18
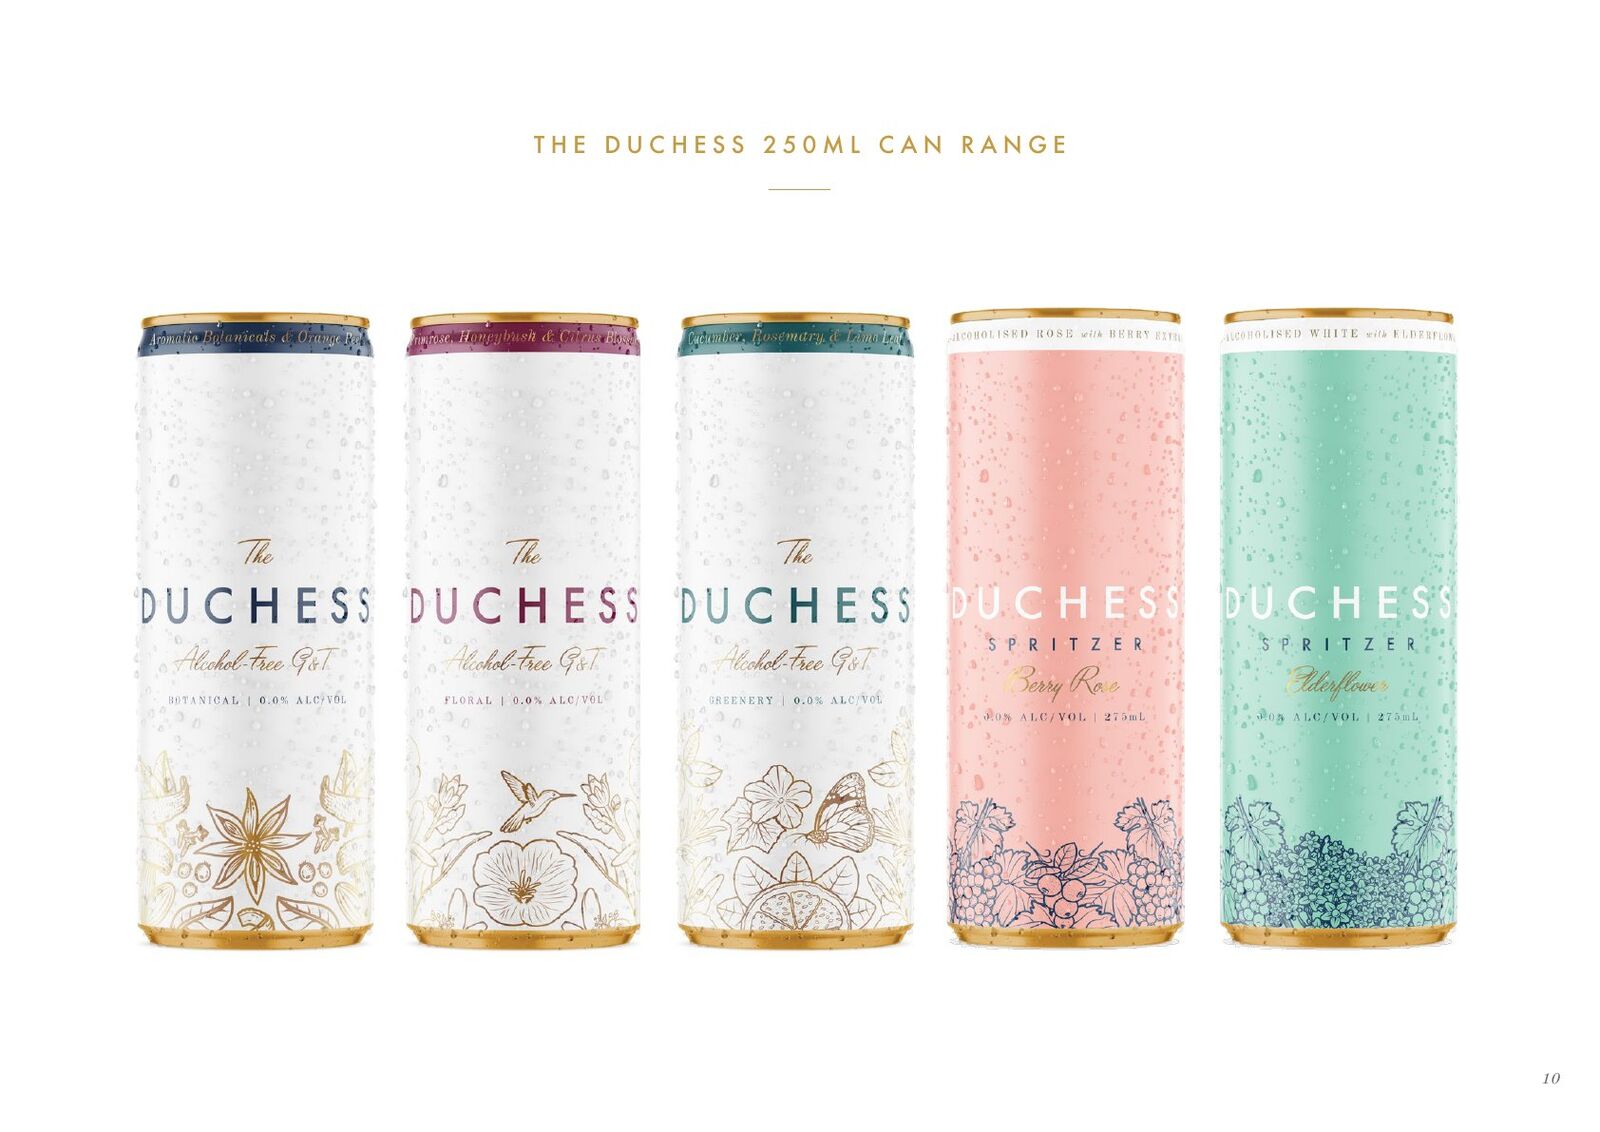
The Duchess 250ml can range
Worked. Pretty product photography.
Off (in hindsight). Same critique as slide 5 — no economics, no occasion, just product. Four of five cans here are repeats of the bottles on slide 5 in a different format. Half a slide of new content stretched to a full slide.
Today's fix. Cut the slide, or use the slot to show cans + bottles together with format-specific velocity data — "cans index 1.4× bottles in convenience-store channel."
Slide 12 of 18
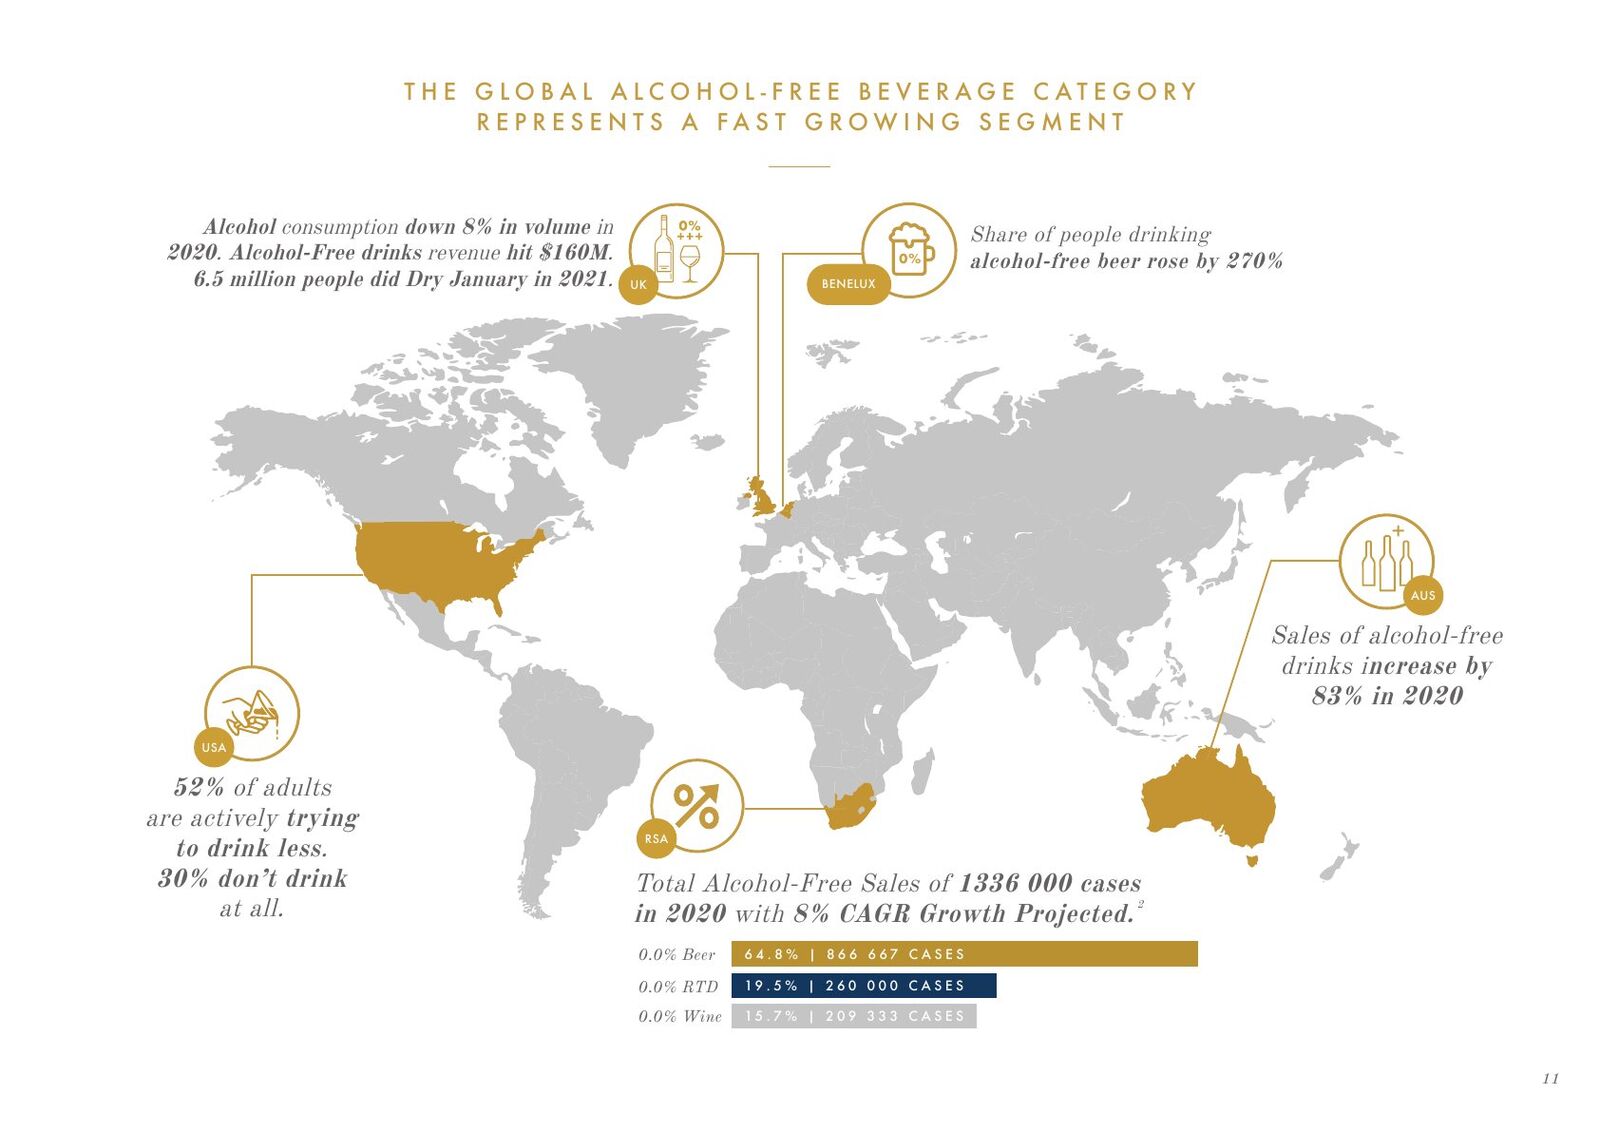
The global alcohol-free beverage category represents a fast-growing segment
Worked. World map with multi-country stats. Visually clean.
Off (in hindsight). Stats are 2020 in a 2021 deck — fine. But "Alcohol-Free drinks revenue hit $160M" is missing geography (UK only? global?). Every stat is uncited. Investors red-pen un-cited numbers.
Today's fix. Cite. "Source: IWSR 2021" under each number. Cited stats get trusted; un-cited ones get discounted.
Slide 13 of 18
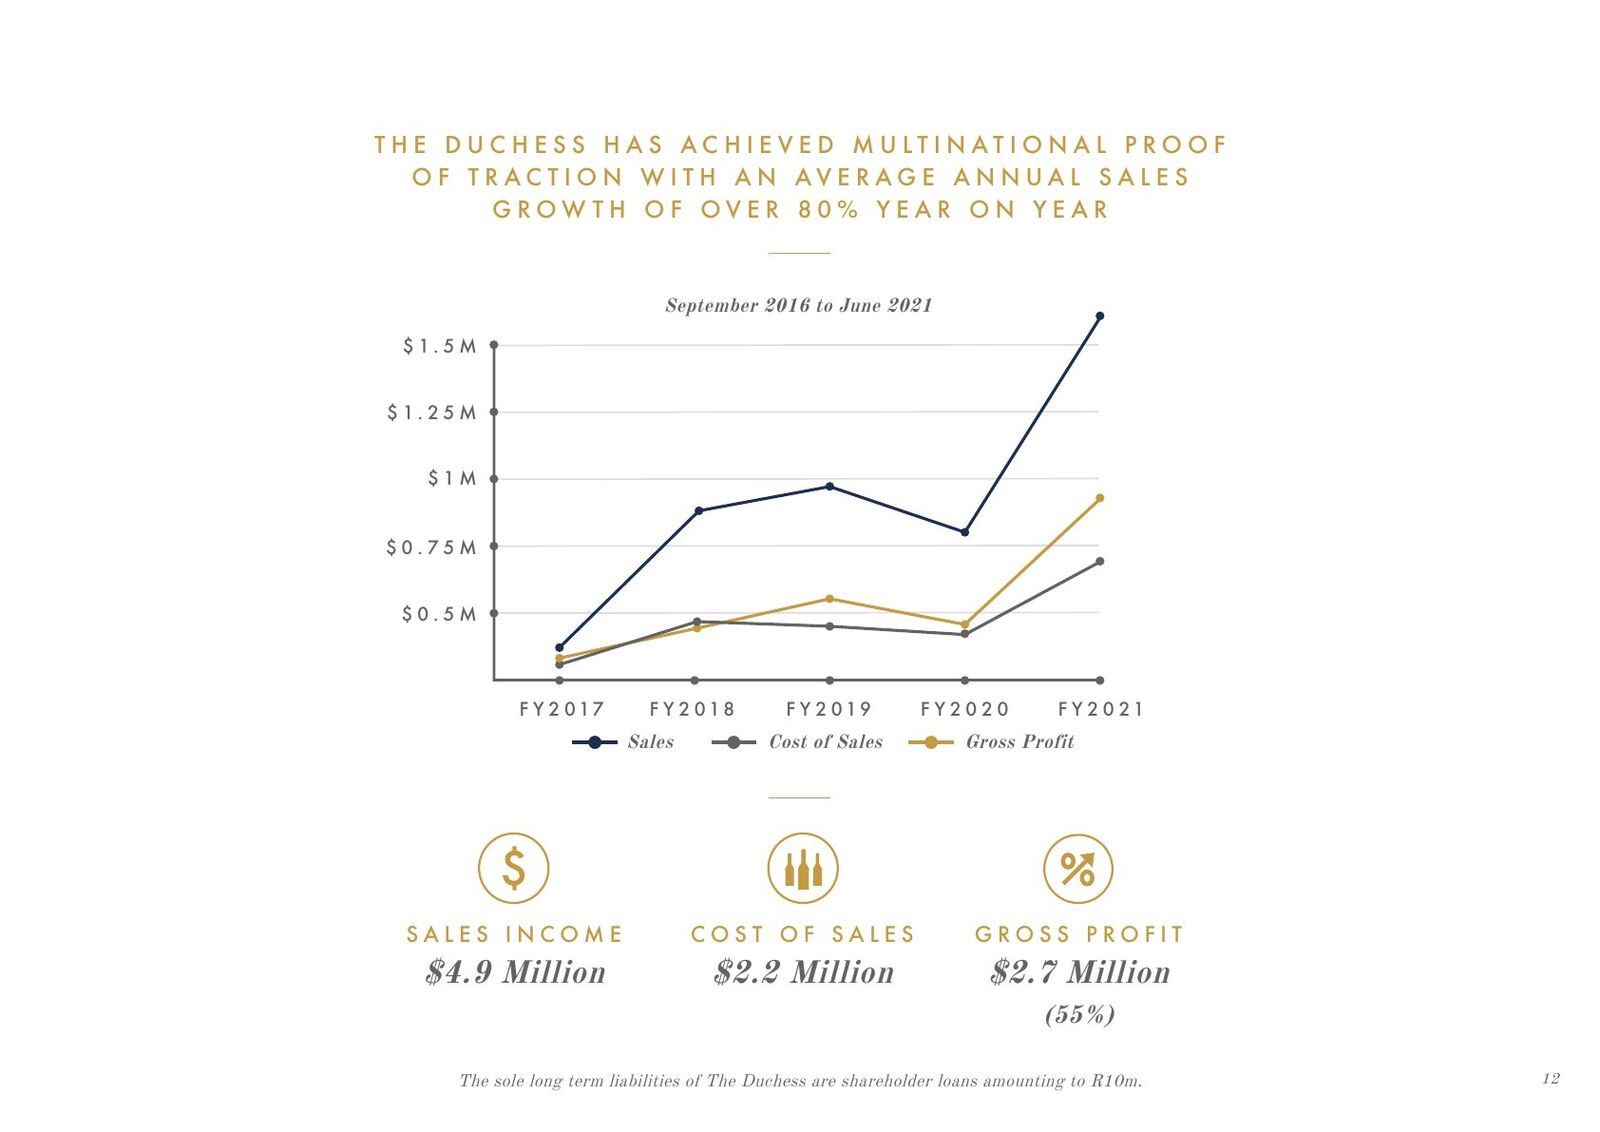
The Duchess has achieved multinational proof of traction (FY2017–FY2021)
Worked. Five years of actuals. Sales + Cost of Sales + Gross Profit on one chart. Honest about the FY2020 dip (COVID).
Off (in hindsight). $4.9M sales · $2.7M GP · 55% margin. On slide 2 we said "110% growth in revenue" — that came on top of what base? Cross-slide arithmetic should reconcile to one consistent number.
Today's fix. Annotate the chart with the FY2020 → FY2021 % growth and the FY2021 / FY2017 multiple. Self-explanatory > inferred.
Slide 14 of 18
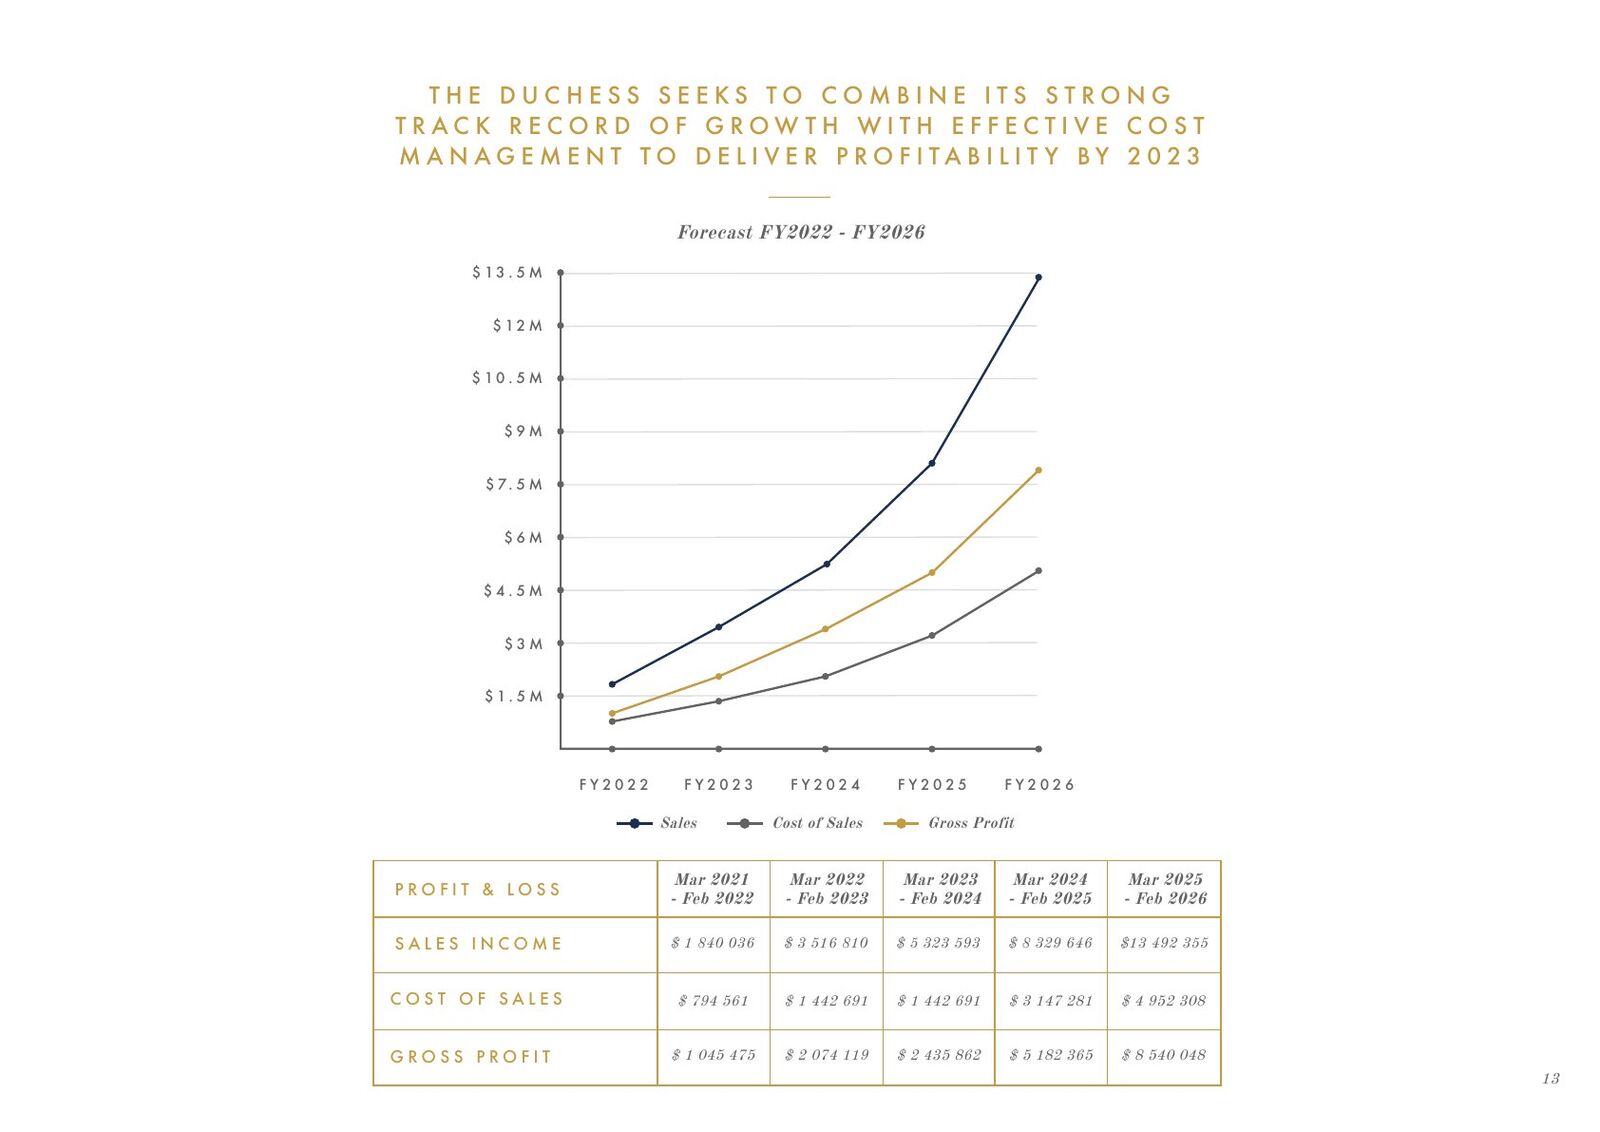
The Duchess seeks to combine its track record with cost management to deliver profitability by 2023
Worked. Hockey stick to $13.5M with 60% GP. Aggressive but defensible given platform.
Off (in hindsight). No assumption table. "FY2024 sales income $5.3M" assumes how many units, in how many markets, at what avg net price?
Today's fix. Assumption strip at the bottom: "FY2024 = 4M units @ $1.33 avg net, 3 active markets (SA + NL + AU), 2 SKU launches." Three numbers turns a forecast into a business plan.
Slide 15 of 18
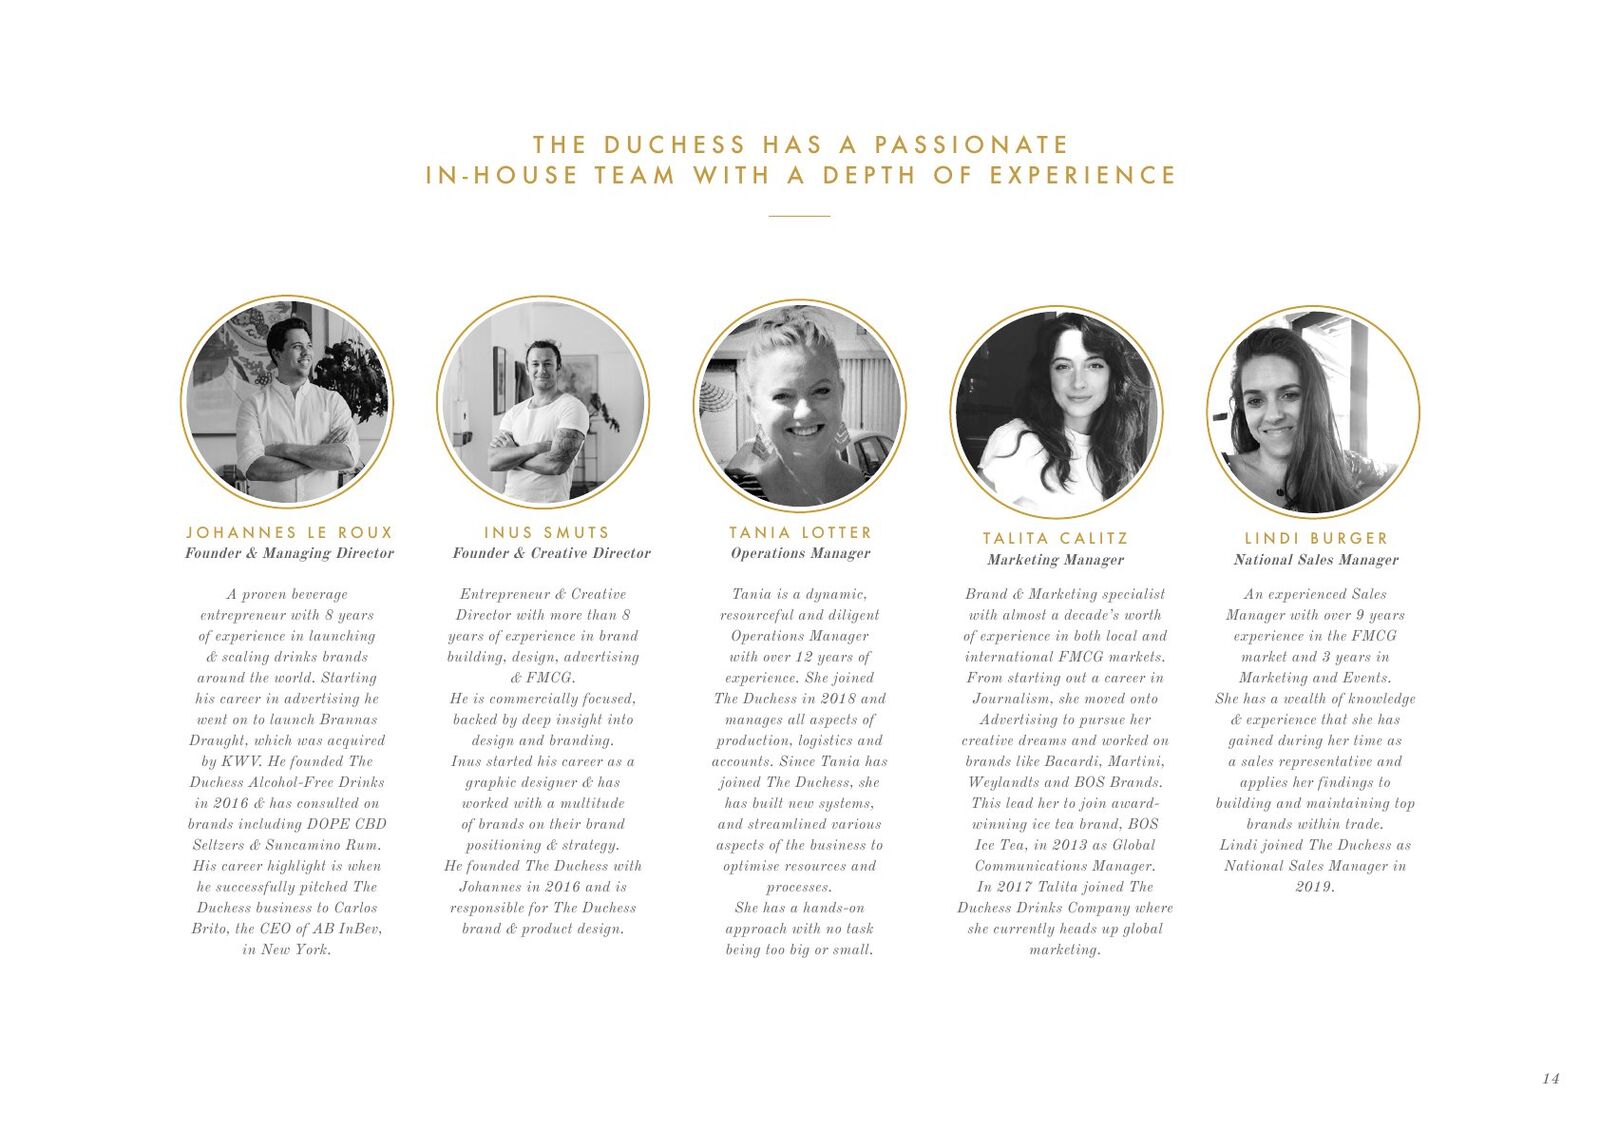
The Duchess has a passionate in-house team with a depth of experience
Worked. Five faces, real bios, named prior ventures (Brannas Draught, BOS Ice Tea, Bacardi/Martini/Weylandts).
Off (in hindsight). My bio reads like a CV ("Brannas Draught, acquired by KWV"). Inus's reads like a CV. The team page should answer "why this team for this brand" — not list jobs.
Today's fix. Reframe each bio around the Duchess-specific skill. Mine: "Brannas to KWV taught me how to sell into an FMCG giant — applying that playbook to AB InBev." Inus: "Designed Brannas, designed The Duchess; same hand, both brands." Talita: "Built BOS Ice Tea's global voice; doing the same here." Pattern-match each bio to the company being pitched, not the LinkedIn version.
Slide 16 of 18
Why invest in The Duchess
Worked. Six-tile recap. Closing line: "Our mission is to build a healthy, profitable & scalable business that would naturally become an acquisition target for global beverage companies" — explicit acquisition-as-thesis.
Off (in hindsight). "A passionate team", "Beautiful brand", "Innovative range" — descriptors, not arguments. And the explicit acquisition language reads "we're built to flip" — true, but stating it baldly discounts founder commitment.
Today's fix. Each tile = one specific number/fact. Passionate team → "5 full-timers, 0 attrition since 2018." Market-leading distribution → "Day 1 access to 55,000 AB InBev SKU-active stores in SA." Beautiful brand → "Two Innobev awards in 2018." Drop the explicit acquisition language; the financials telegraph it.
Slide 17 of 18
Contact
Worked. One email, clean.
Off (in hindsight). 2021-me underestimated the close. No Calendly, no data room link, no deadline.
Today's fix. Today: "Closing tranche by [date]. Data room on signed NDA. Book a call: [link]."
Slide 18 of 18
Disclaimer
Worked. Boilerplate ZA/UK securities-law-compliant.
Off (in hindsight). Two columns of small text on a final slide. Acceptable for a regulated investment proposal.
Today's fix. Optional — move to appendix or separate cover-letter doc to keep the narrative deck under 17 slides.
What this deck taught me
- Timeline-as-traction is undefeated. Slide 6 is the strongest single slide I've ever shipped. Reuse in every venture deck.
- Lead with the partnership punchline. ZX/AB InBev was the credibility multiplier — putting it on slide 2 was right; the moat slide (slide 9) should have followed immediately.
- Internal quotes ≠ social proof. Talita as a positioning quote was a familiar mistake; replace with retailer or category-manager quotes.
- Cover-promise vs. product-page consistency. "Alcohol-Free" on the cover, 6% ABV spritzers on slide 5 — the kind of inconsistency a careful buyer flags.
- Recap slides deserve specifics. Tile-recaps with descriptors instead of numbers is a pattern across every deck I've built. Easiest fix, highest impact.
- Cite every stat. Costs five minutes. Earns trust.
- Close with a forcing function. Even in 2021, a Calendly link plus a deadline would have shortened the close.
If I had to re-cut this deck for 2026 in 12 slides
- Cover (with raise, ask, date, contact)
- ZX/AB InBev punchline (current slide 2, with reconciled growth math)
- AB InBev moat slide (current slide 9)
- Timeline 2016–2021 (current slide 6, the closer)
- ICP + #sobercurious wedge (current slide 4, with external quote)
- Product range (current slide 5, with cover-promise alignment)
- Operations + economics (current slide 7, with margin per bottle)
- UK + California expansion (current slide 10, Live vs. Pipeline)
- Financials + forecast (slides 13 + 14, merged with assumption strip)
- Team (rewritten as founder-market fit)
- Why Invest (specific numbers, not descriptors)
- Ask + use of funds + milestone gates + CTA
Appendix: disclaimer, cap table, advisor bios, market detail, sourcing.
One more time
Want the original PDF in your inbox?
Drop your email below. I'll send you the unannotated deck and nothing else unless you ask.